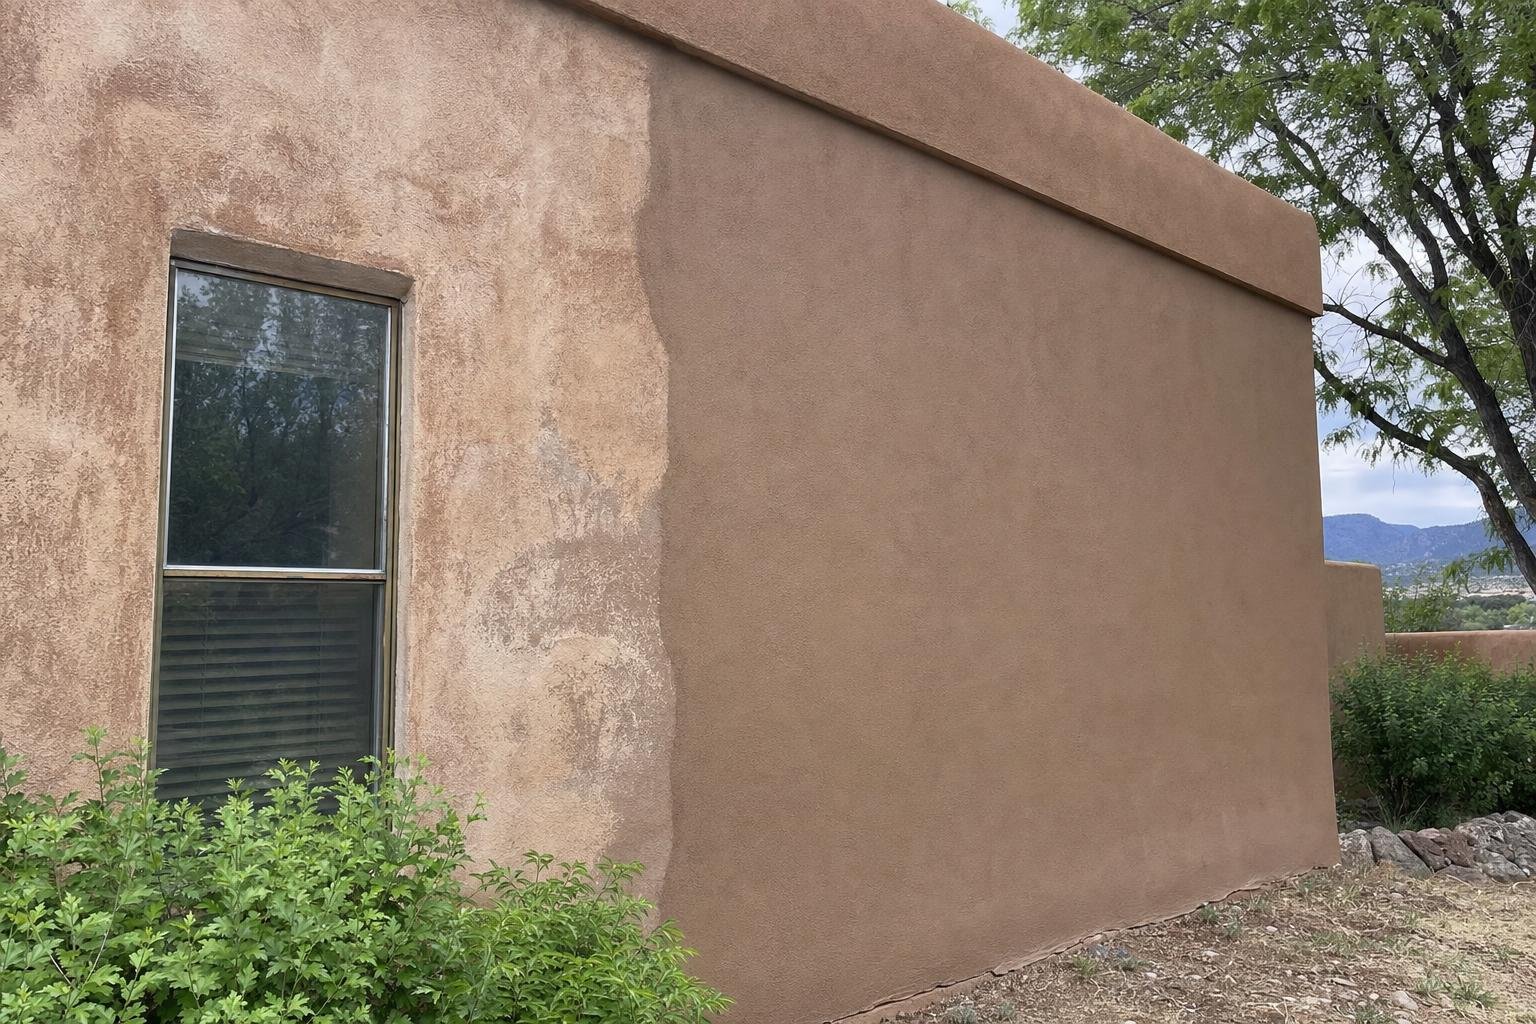
It depends on what caused the damage and whether you can document that cause. Sudden damage often gets reviewed. Wear and age almost never do. This page covers where that line usually falls, what to gather before you call your insurer, and what we can put in writing for you.
When stucco damage is most likely to be covered
Homeowners policies are written for sudden events, not slow deterioration. A tree limb coming down on a wall in a storm, hail pocking the surface, or a vehicle clipping the corner of the house are the kinds of incidents an insurer will generally look at. A pipe that fails behind the wall can also qualify, since the stucco has to come off to reach it. How the policy words water damage and where the leak started matters a great deal there.
What usually isn't covered is gradual cracking from settling and surface weathering that built up over years. Winter freezes in Santa Fe are only occasional, but the freeze-thaw movement that follows can open cracks, and insurers treat those as maintenance, not a sudden event. Read your policy for the difference between a covered peril and wear and tear before you spend time on a claim.
For the hands-on side, see stucco crack repair. Want stucco repair in Santa Fe? Our home page covers it.
Do cracks in stucco count as covered damage?
Three things decide it: how big the crack is, what caused it, and whether you can point to a specific event. A hairline crack from normal shrinkage or settling almost never qualifies, because insurers see it as upkeep. A crack that appeared right after an impact is more likely to be reviewed as covered damage.
A visible crack does not mean coverage. The adjuster is there to decide the cause, and if it points to age, soil movement, or long-term moisture, the claim gets denied. Some cracks that look cosmetic are really a sign of water getting behind the wall through a failed joint or flashing. In that case the question becomes what caused the water entry, and that is worth having looked at before you assume either answer.
What documentation matters for a stucco insurance claim
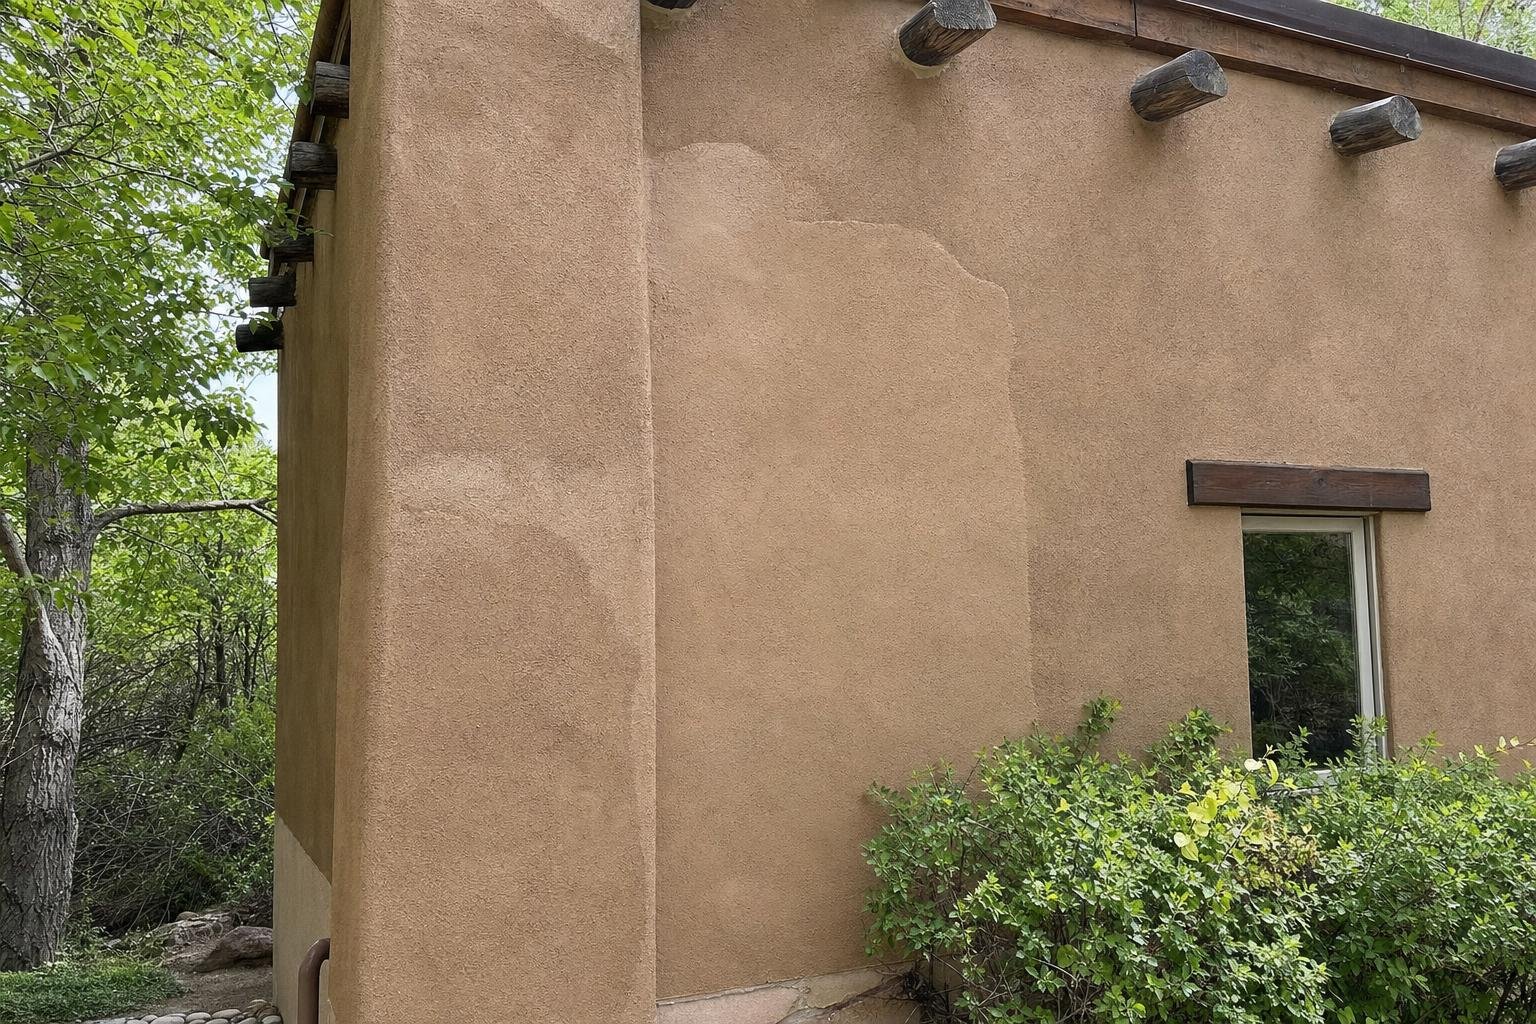
Insurers want to know what happened, when, and what the damage looks like now. Take photos up close and from a distance. Write down the date and the weather event if a storm did it. If a pipe leaked, note where it was and when a plumber was called. Keep any records of earlier repairs.
When we assess a wall, we look behind the surface as well as at it. We check the water-resistive barrier, the flashing at openings and the wall base, the sealed joints around windows, doors and penetrations, and whether the lath is damaged or corroded. Water that has traveled well beyond a single crack or hole tells a different story than a surface blemish, and a written description of what we found behind the stucco shows the extent of the problem, not just the symptom. That description goes in writing along with our read on the cause and the repair scope.
How we work with an open or possible claim
There are two points where we usually come in. Before you file, we can assess the damage and give you a report on the likely cause and repair scope, so you know what you are asking the insurer to cover. After a claim is approved, we can write a line-item estimate that breaks out the scope of work, materials and cost.
Call and we will quote a typical range over the phone. Hole repair runs about $225 to $400 per hole. Water-damage repair is figured by area, at about $25 to $45 per square foot.
We are not adjusters and we cannot say what an insurer will decide. What we can give you is a clear report and a plain estimate, whether you are paying out of pocket or the claim moves forward.
Getting a specific read on your situation
Photos help, but nothing replaces standing at the wall and checking the flashing to see whether the damage is on the surface or part of something larger. If you have an open claim, or you are deciding whether to file one, a contractor's assessment gives you something concrete to hand the adjuster. Call or send us a message and we will set up a time to come out to your Santa Fe home.
What It Typically Costs
The figures here give you a sense of scale, and the final price goes in writing before anything starts.
About $30
$7–$18 per sq. ft.
$3.50–$4.50 per sq. ft.
Also Available
A quick call is a fine place to start, and you decide what happens next.
Updated October 2026